Why Everyday Americans May Choose to Work Until They Die The Retirement Crisis Explained
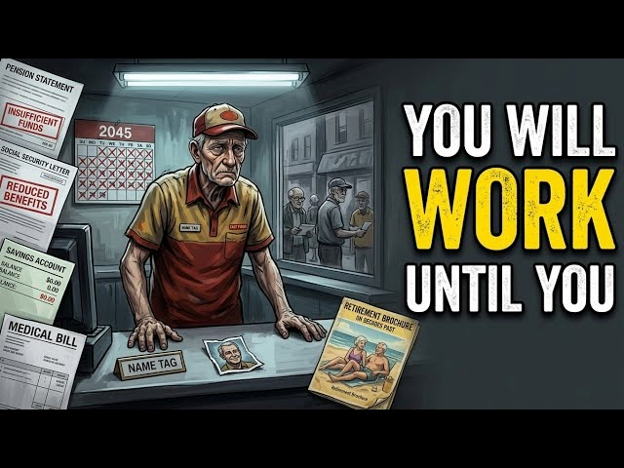
For a huge share of working Americans, that gap isn't closing through better saving habits alone — it's closing through the quiet decision to keep working well past the age they once assumed they'd stop, sometimes indefinitely.
The Fear Behind the Headline
"Working until you die" sounds like an exaggeration, but it's become a real enough anxiety that researchers are now measuring it directly. According to new research from the National Institute on Retirement Security, 61% of Americans are concerned they won't achieve financial security in retirement, and nearly eight in ten say the average worker simply cannot save enough on their own to retire securely. TIAA's CEO recently described the country's roughly $4 trillion retirement savings shortfall as a genuine crisis, warning that close to 40% of Americans are at risk of running out of money in retirement altogether.
That pessimism isn't limited to people who are still decades away from retirement. Even among current retirees, confidence has slipped. The Employee Benefit Research Institute's most recent Retirement Confidence Survey found worker confidence in having enough money to live comfortably dropped from 67% to 61% year over year, while confidence among retirees themselves fell from 78% to 73%.
The Numbers That Explain Why People Feel This Way
It's worth sitting with the actual figures here, because they explain the mood better than any survey question could. A recent study of retired Americans found they believe new retirees need an average of $823,800 in savings and investments to retire comfortably in 2026 — a huge jump from the $580,310 figure people cited just the year before. The typical retiree, meanwhile, actually has around $288,700 saved, less than 40% of what they believe is necessary. Fewer than one in four retirees had even half a million saved when they stopped working.
The picture looks even more precarious for people who haven't retired yet. Research from the National Institute on Retirement Security, drawing on Census Bureau data, found the median amount saved for retirement across all working Americans, including those with nothing saved at all, is just $955. Even among workers who do have retirement accounts with a positive balance, the median sits at $40,000, which sounds like real progress until you compare it against that $823,800 target. Typical employee contribution rates to workplace retirement plans run around 5-6%, with employer contributions adding just under 3% on top, numbers that simply don't compound into a seven-figure nest egg over a normal working life for most people.
Why "Just Work Longer" Has Become the Default Plan
Faced with that gap, working longer isn't really a lifestyle choice for a lot of people anymore, it's closer to the only lever left to pull. The logic is straightforward: every additional year in the workforce is a year you're not drawing down savings, a year your Social Security benefit continues building if you delay claiming it, and a year your existing investments get to keep compounding. For someone who's behind on savings by hundreds of thousands of dollars, that math matters more than any single tip about cutting back on subscriptions or dining out less.
This shift shows up in the labor force projections too. Older workers are expected to account for a remarkable 57% of all labor force growth over the coming decade, a trend that reflects both people choosing to stay employed longer and, for plenty of others, needing to. Nearly one in three retirees in 2025 reported cutting back on essentials like groceries and medical care just to make their existing income stretch, which is the kind of detail that makes "work longer" look less like ambition and more like necessity.
Social Security Isn't the Backstop It Used to Feel Like
Part of what's fueling this anxiety is a growing recognition that Social Security, long treated as the guaranteed floor under retirement planning, is facing its own funding problems. The Social Security Trustees' most recent projections show that without Congressional action, the trust fund faces a shortfall around 2035, at which point benefits could be reduced to roughly 83% of their scheduled amount. For a retiree currently receiving around $2,071 a month, that would mean an actual cut of roughly $352 a month, a meaningful hit for anyone relying on that check as their primary income. The 2.8% cost-of-living adjustment for 2026 helps at the margins, but it hasn't kept pace with the underlying erosion in purchasing power that's built up over the past few years.
What This Actually Means If You're Trying to Avoid This Trap
The uncomfortable truth is that there's no single trick that closes a six-figure savings gap overnight. But a few concrete moves genuinely help. If your employer offers a 401(k) or 403(b) match, contributing enough to capture the full match is one of the few guaranteed returns available anywhere in personal finance, and skipping it is effectively leaving free money behind. In 2026, workers can defer up to $24,500 into a 401(k), with an additional $8,000 catch-up contribution available for those 50 and older, and a notably higher $11,250 catch-up limit for those between 60 and 63 specifically. Automating contribution increases with every raise, rather than letting a higher salary simply raise your spending instead, is a small habit that compounds meaningfully over a couple of decades.
For workers without access to an employer plan, opening a Traditional or Roth IRA is a reasonable substitute, and new rules phased in starting in 2025 now require many newly created 401(k) and 403(b) plans to automatically enroll eligible workers, which should modestly improve participation rates going forward, even if it does little for people already well into their careers with minimal savings.
FAQs
1. How much do Americans think they need to retire comfortably?
Recent survey data puts that figure at an average of $823,800, up sharply from $580,310 the year before, reflecting rising cost-of-living expectations.
2. How much does the average American actually have saved for retirement?
Among all working Americans, including those with no savings, the median amount saved is just $955. Among retirees, the average saved balance is roughly $288,700.
3. Is Social Security going to run out of money?
Not entirely, but without Congressional action, the trust fund is projected to face a shortfall around 2035, which could reduce scheduled benefits to about 83% of their current level.
4. What can I do right now if I feel behind on retirement savings?
Prioritize capturing your full employer match if one is offered, use available catch-up contributions if you're 50 or older, and automate contribution increases tied to raises to build savings steadily over time.
Latest Posts