Fire-Boltt, Noise, Titan Smart The Smartwatch Price War Heating Up India
The price war that engulfed Indian markets from 2020 to 2023, turned India into the world’s biggest smartwatch market with Indians shifting towards more health-conscious and tracking gadgets. But today, the market has witnessed a consistent decline in shipments for ten consecutive quarters and the brands that competed and dominated the markets including Noise, Fire-Bolt and Titan are now competing on different parameters with a focus on survival and curated appeal for the premium buyers.
Table of Contents
1. The Market at a Glance
2. How the Price War Started
3. Fire-Boltt: From Market Leader to Third Place
4. Noise: The Volume Leader That Stopped Chasing Volume
5. Titan Smart: The Premium Bet
6. The Three Brands Compared
7. What Has Changed for Buyers and Retailers
8. What Analysts Expect Next
9. Conclusion
The Market at a Glance
In 2023, Indian markets held a 29.4% share of the global overall wearables market but that majority quickly dipped down to 25.3% by 2024. In 2025, it witnessed another significant decline of 17.6% in terms of smartwatch units sold, with only 28.9 million smartwatches being shipped across 2025. Whereas in 2026, the shipments continued the decline pattern with the second quarter only witnessing 6.38 million units being sold, another 4.0% decline over the previous quarter while marking the tenth consecutive quarterly decline in the past three years And while the quantity being sold decreased, the industry witnessed a boom in prices with smartwatches rising 11.7% in 2025. Reports focusing on the second quarter of 2026 revealed that the average selling cost of a smartwatch in India has risen to $27.3 from $22.0 in 2025, meaning that while there were still plenty of options within the smartwatch market, the budgeted section was experiencing lesser options than before.
|
Indicator |
Figure |
Source |
|
Smartwatch shipments, 2025 |
28.9 million (-17.6% YoY) |
IDC |
|
Smartwatch shipments, Q2 2026 |
6.38 million (-4.0% YoY) |
IDC via TelecomLead |
|
Consecutive quarters of decline |
10 |
IDC via TelecomLead |
|
Average selling price, 2025 |
$26.5 (+11.7%) |
IDC |
|
Smartwatches priced under $50, Q2 2026 |
91.6% |
IDC via Global Brands Magazine |
|
Active smartwatch brands, 2024 to Q1 2025 |
Fell from 80 to 58 |
Counterpoint Research via Global Brands Magazine |
How the Price War Started
The 2020-2023 boom in prices and demand was built upon the shift in becoming health conscious while being boosted through low prices, further compounded on with online flash sales. According to TechCrunch’s records, smartwatches from Indian brands like Fire-Boltt, boAt and Noise in 2024 were based around the $12 price while Apple's entry-level smartwatch started from the $360 mark. Furthermore, according to IDC data, several other smaller or relatively less-known brands also witnessed a growth of market share from 3-5% in 2020 to 15 to 20% by 2023. The numbers were however quick to change with Shipments experiencing an instant decline of over 30% in 2024, a change that was then attributed to longer replacement cycles across smartwatches as well as a decline in the first-time buyers population coupled with aggressive price competition. IDC analyst Vikas Sharma also pointed out that "innovation fatigue" was a prime reason, since most local brands had begun to launch newer models without significant developments or additions to their previous models.
Fire-Boltt: From Market Leader to Third Place
Fire-Boltt, a bootstrapped company, has maintained a lead and domination over India's smartwatch market for most of two years with roughly 30% of the market share in 2023. However, those numbers have witnessed a decline with Counterpoint reporting its market share at 19% as the second leading share in 2024, following which the company witnessed a drastic 54% drop on its shipments as compared to the previous year (according to market-share data compiled by Accio.
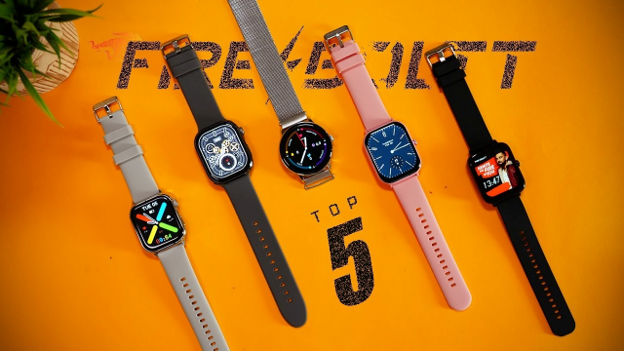
IDC's 2025 data placed Fire-Bolt as the third largest market share holder with over 9.7% of the market. Over the last two years, Fire-Bolt has also focused on diversification and secured its place within the top three leaders as per market share in the smart glasses category while garnering a 17.1% share before rising to rank amongst the leaders again in Q2 2026. More recently in June 2026, Fire-Boltt through a partnership with Flipkart also announced its move into the smartphone segment under the “Boltt” brand building upon its vision of being a diversified entity.
Noise: The Volume Leader That Stopped Chasing Volume
Noise, run by Nexxbase, has managed to sustain its top ranking in IDC’s rankings throughout 2023-2026 with a significant 26.6% market share in 2025, followed by boAt with a 14.1% market share and Fire-Boltt with a 9.7% share. The share further increased upto 30.9% in 2025, ensuring that it remained the leading giant within the smartwatch segment. In Late 2024, Noise was reported to have shifted its focus from focusing on obtaining a larger volume, a shift that was depicted through its 26% decline in shipment despite holding a significant 27% share of the Indian Smartwatch market. In IDC's overall wearables ranking for Q2 2026, which includes earbuds, boAt was first, followed by the OPPO group, Noise, GoBoult and Fire-Boltt.
Titan Smart: The Premium Bet
Titan began its entry into the smartwatch segment with a different focus and witnessed a 35% significant growth in 2024 for its smartwatch shipments while also doubling its market share for the segment within six months. However, the company then pivoted their focus back to the premium and analogue watch segment in 2025 which led to a 21% decline in shipments in the second quarter of 2025.
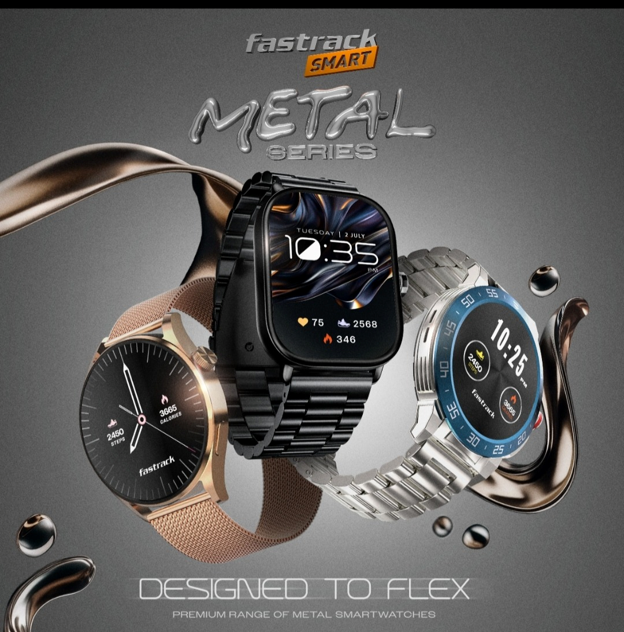
Titan’s smartwatch segment also runs through its affiliation with the Fastrack sub-brand with the ₹3,999 Fastrack MYND model having been launched in 2025 with a focus on AI before being followed up by the Revoltt range for the budget segment within the same year. With these set as the base entry-level models, Titan Smart range is curated for the premium users looking for higher quality and package of features and design.
The Three Brands Compared
|
Noise |
Fire-Boltt |
Titan Smart / Fastrack |
|
|
Position |
Volume leader, mass market |
Former leader, budget-focused |
Premium-leaning, plus budget Fastrack line |
|
IDC smartwatch share, 2025 |
26.6% (first) |
9.7% (third) |
Not in IDC's top five |
|
Trajectory |
Led through the decline |
Fell from ~30% (2023) to 9.7% (2025) |
Grew in 2024, fell in Q2 2025 as focus shifted |
|
Expansion beyond watches |
Wearables and earwear |
Smart glasses, smartphones |
Analogue and premium watches |
Share figures for Fire-Boltt come from two different trackers, Counterpoint and IDC, which measure the market differently.
What Has Changed for Buyers and Retailers
For the sellers as well as the consumers, where the watches are being sold is experiencing a significant shift. Across 2025, a 22.7% decline in online smartwatch shipments was observed while offline sales grew from 37.8% to 40.7% of wearable sales. So far in Q2 2026, online smartwatch volumes have further fallen by 7.3% while offline smartwatch sales have remained largely stable. Many analysts from IDC also predicted that if smartwatch prices were to keep rising, the consumer consensus might begin to shift towards purchasing after seeing in person after comparisons over digital purchases. Notably, another significant trend being noticed is within the features segment of the watches with brands beginning to focus on advanced health sensors, NFC support and AI-driven health insights.
What Analysts Expect Next
According to IDC analysts, smartwatch shipments are predicted to decline further across 2026, with consumers set to begin prioritizing higher-value, health-centric products over budget preferences. For the current quarter, the pivot from volume to value is bound to be significant with the ASPs predicted to continue their climb while for the entire year, experters believe that Wristbands and smart glasses are expected to be among the fastest-growing pockets, from a small base, in the second half of the year.
Conclusion
The Indian Smartwatch market is no longer contested on the basis of who gains the larger share between Fire-Bolt, Noise and Titan but rather who survives in a category that is constantly witnessing decline in volume sales, depletion of brands and models across the markets along with rising prices and a declining consumer spread. As things stand, Noise has managed to maintain its lead while Fire-Bolt has shifted its focus towards diversifying and Titan attempts to capture the premium end. With the festive season approaching, the next quarter could define whether the market invites another round of our price discounting to attempt and raise volumes and whether it is successful in stabilizing at a smaller level but pricier level.
Latest Posts